Navigating Inflation: Fixed-Income Investments in 2026
Anúncios
The Impact of Current Inflation on Fixed-Income Investments: Protecting Your Portfolio in 2026
In the dynamic world of finance, few factors command as much attention and concern as inflation, especially when considering its profound implications for fixed-income investments. As we look towards 2026, the current inflationary environment presents a complex challenge for investors seeking stability and reliable returns. Understanding how inflation erodes purchasing power and devalues future cash flows is crucial for anyone holding or considering fixed-income assets. This comprehensive guide will delve into the intricate relationship between inflation and fixed-income investments, offering actionable strategies to protect and optimize your portfolio in the coming years. We will explore the mechanisms through which inflation impacts various fixed-income instruments, analyze the current economic landscape, and provide forward-looking insights to help you navigate the uncertainties of 2026.
The global economy has been grappling with elevated inflation levels, a phenomenon driven by a confluence of factors including supply chain disruptions, robust consumer demand, geopolitical tensions, and expansive fiscal and monetary policies. While central banks worldwide have been aggressive in their efforts to tame inflation through interest rate hikes, the path to price stability remains uncertain. For investors in fixed-income securities, this uncertainty translates into heightened risk. Bonds, traditionally seen as safe havens, become particularly vulnerable during periods of rising inflation because their fixed coupon payments lose value in real terms. The principal amount returned at maturity also suffers from reduced purchasing power, diminishing the overall real return on investment. Therefore, understanding the nuances of fixed-income inflation 2026 is not merely academic; it is an imperative for prudent financial planning.
This article aims to equip you with the knowledge and strategies necessary to mitigate the adverse effects of inflation on your fixed-income portfolio. We will examine different types of fixed-income instruments, from government bonds to corporate debt, and assess their varying sensitivities to inflationary pressures. Furthermore, we will discuss advanced strategies such as inflation-indexed securities, floating-rate notes, and diversification techniques that can serve as powerful tools in your investment arsenal. By the end of this read, you will have a clearer picture of how to position your fixed-income investments for resilience and growth in a challenging inflationary environment, ensuring your financial goals remain within reach even as the economic currents shift towards 2026.
Anúncios
Understanding Inflation’s Erosion of Fixed-Income Value
At its core, inflation represents the rate at which the general level of prices for goods and services is rising, and consequently, the purchasing power of currency is falling. For fixed-income investments, this phenomenon is particularly detrimental. When you invest in a bond, you essentially lend money to an issuer (government or corporation) in exchange for periodic interest payments and the return of your principal at maturity. These payments are typically fixed. If inflation rises, the real value of those fixed payments decreases. For instance, if you receive a 3% coupon payment on a bond, and inflation is running at 5%, your real return is actually negative 2%. This erosion of purchasing power is the primary concern for fixed-income investors in an inflationary climate, making the impact on fixed-income inflation 2026 a critical consideration.
Consider a long-term bond issued with a fixed interest rate when inflation is low. If inflation unexpectedly surges, the fixed interest payments you receive will buy less in the future. Moreover, if interest rates rise in response to inflation, the market value of your existing bond, with its lower fixed rate, will fall. This inverse relationship between interest rates and bond prices means that investors who need to sell their bonds before maturity might incur capital losses. The longer the maturity of the bond, the more sensitive its price is to changes in interest rates and inflation. This duration risk is a key factor that investors must account for, especially as we project potential inflationary pressures into 2026.
Anúncios
Various economic indicators help us gauge inflationary trends. The Consumer Price Index (CPI) is the most commonly cited measure, tracking the average change over time in the prices paid by urban consumers for a market basket of consumer goods and services. Other indicators include the Producer Price Index (PPI), which measures average changes in selling prices received by domestic producers for their output, and the Personal Consumption Expenditures (PCE) price index, preferred by the Federal Reserve. Monitoring these indicators provides critical insights into the trajectory of inflation and its potential impact on fixed-income investments. As we approach 2026, these metrics will be under intense scrutiny, informing investment decisions and policy responses. The persistent challenge of fixed-income inflation 2026 necessitates a proactive approach to portfolio management.
Current Economic Landscape and Inflationary Drivers
The current inflationary environment is a mosaic of interconnected global and domestic factors. Post-pandemic economic recovery fueled robust consumer demand, often outpacing supply capabilities. Supply chain bottlenecks, exacerbated by geopolitical events such as the conflict in Ukraine, have led to higher input costs for businesses, which are then passed on to consumers. Energy prices have also played a significant role, with crude oil and natural gas fluctuations directly impacting transportation and production costs across industries. These pressures contribute significantly to the narrative of fixed-income inflation 2026, making it a complex challenge for investors.
Central banks, including the Federal Reserve, the European Central Bank, and the Bank of England, have responded to surging inflation by implementing aggressive monetary tightening policies. This has primarily involved raising benchmark interest rates, aiming to cool down economic activity and reduce demand. While these actions are designed to bring inflation back to target levels, they also have direct consequences for fixed-income markets. Higher interest rates increase the cost of borrowing for governments and corporations, leading to higher yields on newly issued bonds. This makes existing lower-yielding bonds less attractive, pushing their market values down. The interplay of these forces will continue to shape the landscape for fixed-income investments as we move closer to 2026.
Fiscal policies have also contributed to the inflationary picture. Government spending programs, designed to stimulate economies during downturns, can inject significant liquidity into the system, potentially fueling demand-pull inflation. While necessary during crises, the long-term effects of such policies need careful consideration, especially regarding their impact on debt levels and future inflation. Labor market dynamics are another crucial element; tight labor markets, characterized by low unemployment and rising wages, can contribute to cost-push inflation as businesses face higher labor costs. All these elements collectively paint a picture of the challenges and opportunities for fixed-income inflation 2026.
Strategies for Protecting Fixed-Income Portfolios in 2026
1. Inflation-Indexed Securities (TIPS)
One of the most direct ways to protect against inflation is to invest in inflation-indexed securities. In the U.S., these are primarily Treasury Inflation-Protected Securities (TIPS). TIPS are government bonds whose principal value adjusts with the Consumer Price Index (CPI). When inflation rises, the principal value of TIPS increases, and consequently, the interest payments (which are a fixed percentage of the adjusted principal) also increase. At maturity, investors receive either the original or adjusted principal, whichever is greater. This mechanism provides a built-in hedge against inflation, making TIPS an attractive option for investors concerned about fixed-income inflation 2026.
While TIPS offer excellent inflation protection, it’s important to understand their nuances. Their market price can still fluctuate with changes in real interest rates (nominal interest rates minus inflation). If real interest rates rise, TIPS prices can fall. However, for investors with a buy-and-hold strategy, the inflation adjustment mechanism provides significant comfort. TIPS can be a foundational component of a fixed-income portfolio aiming to preserve purchasing power in an inflationary environment, offering a degree of certainty that traditional bonds cannot.
2. Floating-Rate Notes (FRNs)
Floating-rate notes (FRNs) are another powerful tool in an inflationary climate. Unlike traditional fixed-rate bonds, FRNs have coupon payments that adjust periodically based on a benchmark interest rate, such as the Secured Overnight Financing Rate (SOFR) or LIBOR (though LIBOR is being phased out). As benchmark rates rise in response to inflation, the interest payments on FRNs also increase. This feature makes them less susceptible to interest rate risk compared to fixed-rate bonds, as their market value tends to remain more stable.
FRNs are particularly appealing when interest rates are expected to rise, as they allow investors to benefit from higher rates without having to constantly reinvest in new bonds. This characteristic makes them a valuable asset in a portfolio designed to combat fixed-income inflation 2026. They provide a dynamic income stream that can keep pace with rising prices, thus helping to preserve real returns. However, it’s worth noting that if interest rates fall, the income generated by FRNs will also decrease.
3. Shorter Duration Bonds
Reducing the duration of your fixed-income portfolio is a classic strategy to mitigate interest rate risk, which is closely linked to inflation risk. Duration measures a bond’s sensitivity to changes in interest rates; bonds with longer maturities typically have higher durations and are thus more sensitive to interest rate fluctuations. By investing in shorter-duration bonds (e.g., those maturing in 1-3 years), investors expose themselves to less price volatility when interest rates rise.
While shorter-duration bonds generally offer lower yields compared to their longer-term counterparts, their reduced volatility can be a significant advantage during periods of uncertainty and rising inflation. This strategy allows investors to reinvest their principal at potentially higher rates sooner, benefiting from the upward trend in interest rates. For those concerned about fixed-income inflation 2026, a tilt towards shorter-duration instruments can provide flexibility and reduce exposure to significant capital losses from rising rates.
4. Diversification Beyond Traditional Bonds
Relying solely on traditional government or corporate bonds in an inflationary environment can be risky. Diversifying into other asset classes and alternative fixed-income-like instruments can provide additional layers of protection. This includes:
- High-Yield Bonds: While carrying higher credit risk, high-yield bonds (junk bonds) often offer higher coupon rates that can provide a buffer against inflation. They are also sometimes less sensitive to interest rate changes if their performance is more driven by credit spread movements.
- Bank Loans (Leveraged Loans): These are senior secured loans made to corporations, typically with floating interest rates. Similar to FRNs, their interest payments adjust with benchmark rates, making them attractive in a rising rate environment.
- Real Estate Investment Trusts (REITs): While not strictly fixed income, REITs can offer inflation protection through rising property values and rental income, which often keep pace with or even exceed inflation. They provide a hybrid exposure to real assets and income.
- Commodities: Investing in commodities or commodity-linked instruments can act as an inflation hedge, as commodity prices often rise during inflationary periods.
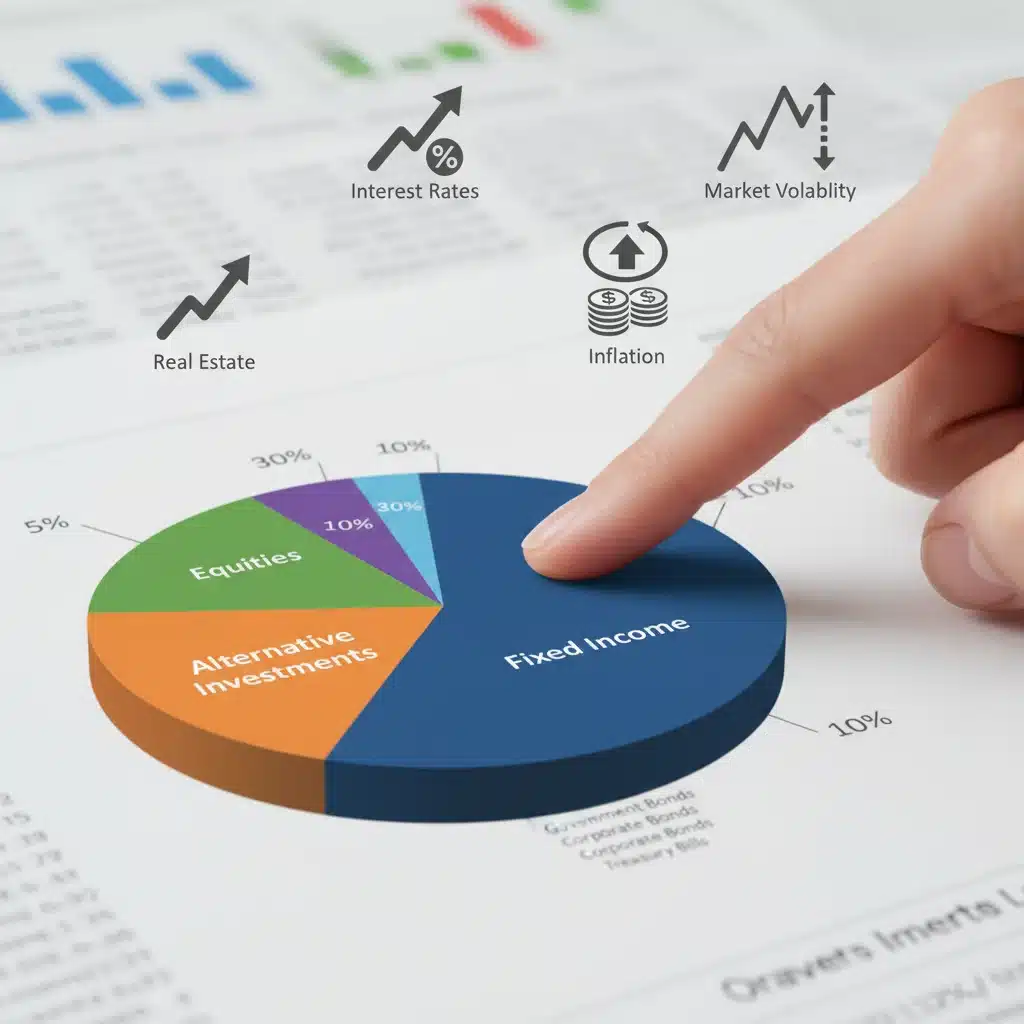
Strategic diversification helps spread risk and provides multiple avenues for potential returns, reducing the overall impact of fixed-income inflation 2026 on your portfolio. It’s about not putting all your eggs in one basket, especially when that basket is particularly vulnerable to specific economic pressures.
5. Active Management and Rebalancing
In an inflationary environment, a passive buy-and-hold strategy for fixed-income assets might not be optimal. Active management, involving continuous monitoring of economic data, inflation indicators, and central bank policies, becomes crucial. This allows investors to make timely adjustments to their portfolios, shifting allocations as market conditions evolve. Rebalancing your portfolio periodically ensures that your asset allocation remains aligned with your risk tolerance and financial goals, especially in the face of changing inflationary pressures.
For instance, if inflation appears to be accelerating, an active manager might increase exposure to TIPS or FRNs and reduce holdings in long-duration fixed-rate bonds. Conversely, if inflation shows signs of decelerating, a more traditional fixed-income allocation might become more appealing. The ability to adapt quickly to new information is a significant advantage in managing fixed-income inflation 2026 effectively. This dynamic approach ensures that your portfolio remains agile and responsive to market shifts.
The Role of Central Bank Policies and Future Outlook for 2026
Central banks play a pivotal role in shaping the inflationary outlook and, consequently, the performance of fixed-income investments. Their primary mandate often includes maintaining price stability, and they achieve this through various monetary policy tools, most notably interest rate adjustments and quantitative easing/tightening. The decisions made by institutions like the Federal Reserve will be critical in determining the trajectory of inflation and interest rates leading up to and throughout 2026.
The current cycle of interest rate hikes has been a direct response to elevated inflation. As central banks continue to assess economic data, their future actions will depend on how quickly inflation cools down and whether economic growth can be sustained without triggering a recession. If inflation proves more persistent than anticipated, central banks might need to maintain higher interest rates for longer, further impacting fixed-income markets. Conversely, if inflation subsides quickly, they might pivot to rate cuts, which would generally be beneficial for bond prices.
Investors must pay close attention to central bank communications, including meeting minutes, speeches by policymakers, and economic projections. These provide valuable clues about future monetary policy directions and their potential implications for fixed-income inflation 2026. The market often reacts swiftly to these signals, making it essential for investors to stay informed and adjust their strategies accordingly. Predicting the exact path of central bank actions is challenging, but understanding their objectives and reactions to economic data can provide a significant edge.
Long-Term Considerations and Personal Financial Planning
Beyond immediate strategies, investors need to consider the long-term implications of inflation for their overall financial planning. Inflation erodes the purchasing power of savings, making it harder to achieve long-term goals such as retirement, education funding, or significant purchases. For those relying on fixed income for retirement, the impact of sustained inflation can be particularly severe, as their income stream does not adjust automatically to rising costs.
Therefore, a holistic approach to financial planning must incorporate inflation protection across all asset classes, not just fixed income. This might involve increasing allocations to equities, real estate, or other real assets that historically have performed well during inflationary periods. For younger investors, the ability to take on more risk in growth-oriented assets can help offset the long-term corrosive effects of inflation. For those closer to retirement, a carefully constructed portfolio with a mix of inflation-protected fixed income and dividend-paying stocks can provide a more resilient income stream.
Regularly reviewing and adjusting your financial plan in consultation with a financial advisor is paramount. A personalized plan can help you understand your specific exposure to inflation risk and tailor strategies to your individual circumstances, risk tolerance, and financial goals. The goal is not just to preserve capital but to ensure that your capital retains its real purchasing power over time, securing your financial future against the backdrop of fixed-income inflation 2026 and beyond.
Conclusion: Navigating Fixed-Income Inflation in 2026 with Confidence
The prospect of continued inflation presents a formidable challenge for fixed-income investors as we look towards 2026. The traditional role of fixed-income assets as a stable, predictable component of a portfolio is significantly tested when purchasing power erodes and interest rates climb. However, by understanding the mechanisms through which inflation impacts these investments and by adopting proactive, strategic measures, investors can effectively protect and even enhance their portfolios.
Key strategies such as investing in inflation-indexed securities like TIPS, utilizing floating-rate notes, shortening bond durations, and diversifying beyond conventional bonds are essential tools in this environment. Active management and continuous monitoring of economic indicators and central bank policies will also be crucial for making timely and informed decisions. The interplay of global economic forces, central bank responses, and market dynamics will undoubtedly create a complex landscape, but with the right approach, investors can navigate these waters successfully.
Ultimately, safeguarding your fixed-income investments in 2026 requires a blend of knowledge, vigilance, and adaptability. By implementing the strategies outlined in this guide, you can work towards preserving the real value of your capital, ensuring that your fixed-income holdings continue to play their vital role in achieving your long-term financial aspirations. The journey through an inflationary period demands careful planning and a willingness to adjust, but with a well-considered strategy, you can face the future of fixed-income inflation 2026 with confidence.