Comparing High-Yield Savings Accounts in 2026: Finding the Best Rates Above 5.0%
In the ever-evolving landscape of personal finance, finding smart ways to make your money work harder for you is paramount. As we navigate through 2026, one of the most effective strategies for maximizing your liquid savings is by opting for high-yield savings accounts. Gone are the days when traditional bank accounts offered negligible returns. Today, a competitive market, coupled with economic factors, has pushed interest rates upwards, making it possible to find accounts offering attractive Annual Percentage Yields (APYs) well above 5.0%.
This comprehensive guide is designed to help you cut through the noise and identify the best high-yield savings accounts available in 2026. We’ll delve into what makes these accounts so appealing, what to look for when comparing options, and ultimately, how to secure a rate that truly helps your money grow significantly. Whether you’re saving for a down payment, an emergency fund, or simply looking to optimize your cash reserves, understanding the nuances of these accounts is crucial.
The Resurgence of High-Yield Savings Accounts: Why Now?
The financial climate leading into 2026 has created a fertile ground for high-yield savings accounts. Several key factors have contributed to this resurgence:
Anúncios
- Interest Rate Environment: Central banks globally, in response to inflationary pressures and economic adjustments, have maintained or slightly increased benchmark interest rates. This trickles down to consumer banking products, allowing institutions to offer more competitive APYs on savings.
- Increased Competition Among Online Banks: The rise of online-only banks and fintech companies has intensified competition. These institutions often have lower overhead costs compared to traditional brick-and-mortar banks, enabling them to pass on savings to customers in the form of higher interest rates.
- Consumer Demand for Better Returns: Savers are becoming more financially savvy and are actively seeking alternatives to low-interest checking and savings accounts. This demand pushes banks to innovate and offer more attractive products.
- Technological Advancements: Digital banking platforms have made it easier than ever to open, manage, and transfer funds between accounts, removing barriers that once deterred people from exploring different banking options.
For individuals, this means a golden opportunity to earn substantial returns on their idle cash. A 5.0% APY, or higher, can significantly accelerate your savings goals compared to the paltry 0.01% or 0.05% offered by many traditional banks.
Understanding Annual Percentage Yield (APY) vs. Interest Rate
Before diving into specific accounts, it’s vital to understand the difference between an interest rate and the Annual Percentage Yield (APY). While often used interchangeably, they are distinct, and APY is the figure you should always pay attention to when comparing high-yield savings accounts.
Anúncios
- Interest Rate: This is the simple rate at which your money earns interest, typically expressed annually.
- Annual Percentage Yield (APY): This takes into account the effect of compounding interest. Compounding means that you earn interest not only on your initial deposit but also on the interest that has already been added to your account. The more frequently interest is compounded (e.g., daily vs. monthly), the higher the APY will be relative to the simple interest rate.
When you see an advertisement for a high-yield savings account, the prominent number will almost always be the APY because it represents the true annual rate of return you will receive, assuming interest is compounded. Always compare APYs to get an accurate picture of which account offers the best return.
Key Features to Look for in High-Yield Savings Accounts Above 5.0%
While the APY is undoubtedly the most attractive feature, a truly excellent high-yield savings account offers more than just a high rate. Here’s a checklist of other important considerations:
1. Minimum Balance Requirements
Some banks require a minimum balance to open an account or to earn the advertised APY. Others might impose a penalty or drop your rate if your balance falls below a certain threshold. Look for accounts with no minimum balance or a manageable one that you can comfortably maintain.
2. Fees and Charges
Beware of hidden fees that can erode your earnings. Common fees include monthly maintenance fees, excessive withdrawal fees, or fees for paper statements. Many online high-yield savings accounts boast no monthly fees, which is a significant advantage.
3. FDIC or NCUA Insurance
Your money’s safety is paramount. Ensure the bank offering the high-yield savings account is insured by the Federal Deposit Insurance Corporation (FDIC) for banks or the National Credit Union Administration (NCUA) for credit unions. This protects your deposits up to $250,000 per depositor, per institution, in case of bank failure.
4. Accessibility and Withdrawal Limits
While savings accounts are generally not meant for frequent transactions, you should still have reasonable access to your funds. Federal Regulation D historically limited certain withdrawals and transfers from savings accounts to six per month. While this regulation was suspended during the pandemic, banks may still impose their own limits. Check the bank’s policy on withdrawals and transfers to ensure it aligns with your potential needs.
5. Online and Mobile Banking Experience
Since many of the best high-yield savings accounts are offered by online banks, a robust and user-friendly online and mobile banking platform is essential. Look for features like easy fund transfers, mobile check deposit, clear statements, and responsive customer support.
6. Customer Service
Even with digital convenience, good customer service is invaluable. Check for various support channels (phone, chat, email) and their availability. Reading reviews can give you an idea of a bank’s reputation for customer support.
Top Contenders: High-Yield Savings Accounts with Rates Above 5.0% in 2026
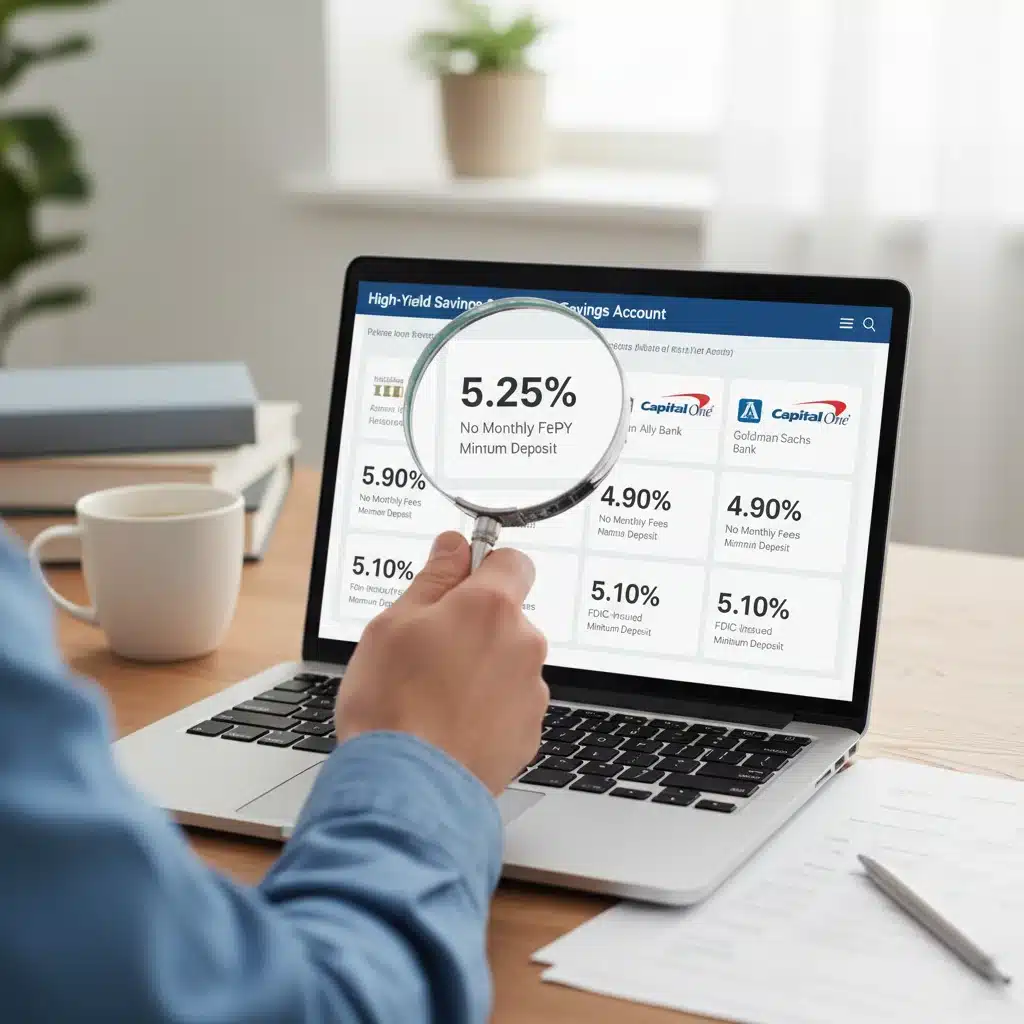
As of early 2026, several financial institutions are leading the charge by offering highly competitive APYs. Keep in mind that these rates are dynamic and can change, so always verify the current rates directly with the bank. Here are some examples of types of institutions and offers you might encounter:
Online-Only Banks
These are often your best bet for the highest rates due to their lower operating costs. Look for names like:
- “Digital Savings Bank X”: Known for consistently high APYs (often 5.10% – 5.30%) with no monthly fees, no minimum balance requirements, and daily compounding. Their robust mobile app and 24/7 chat support make them a popular choice.
- “Fintech Savings Innovators”: Some fintech platforms partner with established banks to offer competitive rates (e.g., 5.05% APY). They might come with additional budgeting tools or investment integration, appealing to a tech-savvy audience.
Credit Unions
While often smaller, many credit unions offer excellent rates, especially to their members. Membership requirements can vary, but they often include living in a certain area or being affiliated with a specific organization.
- “Community Credit Union Z”: Offers a 5.25% APY on balances up to a certain limit (e.g., $10,000 or $25,000), after which the rate might decrease. This can be ideal for smaller emergency funds. They are NCUA insured.
Hybrid Accounts (Checking/Savings Combos)
Some institutions offer combined accounts that provide high APYs on the savings portion, often linked to specific checking account activities (e.g., a certain number of debit card transactions per month, or direct deposit requirements).
- “Smart Money Bank”: Offers 5.00% APY on savings when linked to their checking account, provided you meet certain criteria like 10 debit card purchases per month. This can be a convenient option if you want to consolidate your banking.
Important Note: Always read the fine print. Some accounts might have introductory rates that expire, tiered rates (where higher balances earn different APYs), or specific conditions to qualify for the highest rate.
Strategies for Maximizing Your High-Yield Savings
Once you’ve selected the ideal high-yield savings account, there are several strategies you can employ to make the most of it:
1. Automate Your Savings
Set up automatic transfers from your checking account to your high-yield savings account on a regular basis (e.g., weekly, bi-weekly, or monthly). This ‘set it and forget it’ approach ensures consistent growth without requiring constant effort.
2. Maintain an Emergency Fund
A high-yield savings account is the perfect place for your emergency fund. It keeps your money liquid and accessible while earning a significant return, protecting you against unexpected expenses without resorting to high-interest debt.
3. Save for Specific Goals
Whether it’s a down payment for a house, a new car, a dream vacation, or a child’s education, earmarking funds for specific goals within your high-yield account can provide motivation and help you track progress more effectively.
4. Regularly Review Rates
The market for high-yield savings accounts is competitive and rates can change. Make it a habit to review the top rates periodically (e.g., every 6-12 months). If your current bank’s rate drops significantly, don’t hesitate to switch to a new institution offering a better APY. The process of transferring funds between FDIC-insured online banks is usually straightforward.
5. Understand Tax Implications
The interest you earn from your high-yield savings account is considered taxable income. Keep this in mind, especially if you’re earning a substantial amount, and factor it into your financial planning. You’ll receive a 1099-INT form from your bank if you earn over a certain threshold (typically $10).
Potential Pitfalls and How to Avoid Them
While high-yield savings accounts are generally a fantastic financial tool, there are a few potential downsides to be aware of:
1. Variable Interest Rates
Most high-yield savings accounts come with variable interest rates, meaning the APY can change at any time based on market conditions and the bank’s discretion. While this can work in your favor when rates are rising, it also means your rate could decrease. Stay informed and be prepared to switch if your rate becomes uncompetitive.
2. Withdrawal Limitations
As mentioned, some banks still adhere to or impose their own transaction limits. If you anticipate needing to make more than six transfers or withdrawals per month, a checking account or a money market account might be a more suitable option for those specific funds.
3. Less Personal Interaction
Online banks, while offering great rates, typically don’t have physical branches. If you prefer face-to-face banking or need to deposit cash regularly, this could be a drawback. However, many online banks offer solutions for cash deposits through partnerships or money orders.
4. Introductory Rates
Some banks might offer an exceptionally high APY as an introductory offer for a limited period (e.g., 3 or 6 months). After this period, the rate might drop significantly. Always check if the advertised rate is introductory or a standard ongoing rate.
The Future of High-Yield Savings in 2026 and Beyond
As we look further into 2026, the trend of competitive high-yield savings accounts is likely to continue. The digital transformation of banking, coupled with a consumer base that is increasingly demanding better value, will continue to drive innovation in this space. We may see more personalized banking experiences, integration with AI-driven financial planning tools, and even more dynamic rate structures.
For the savvy saver, this means that the opportunities to grow your money passively will only expand. Staying informed about market trends and being proactive in seeking out the best rates will be key to financial success.
Conclusion: Empowering Your Savings with High-Yield Accounts
In conclusion, high-yield savings accounts offering rates above 5.0% in 2026 represent a powerful tool for anyone looking to maximize their savings. By carefully comparing APYs, understanding fees, ensuring FDIC/NCUA insurance, and considering accessibility, you can find an account that perfectly aligns with your financial goals.
Don’t let your money sit idly in a low-interest account. Take advantage of the current financial climate to supercharge your savings and build a more secure financial future. With the right high-yield savings account, your money won’t just be sitting there; it will be actively working for you, compounding and growing with every passing day. Start your research today and make 2026 the year your savings truly take off!